Your first 90 days of compliance, on one calendar
What a newly incorporated company owes the government, and exactly when: from the 30-day board meeting to the 180-day INC-20A.
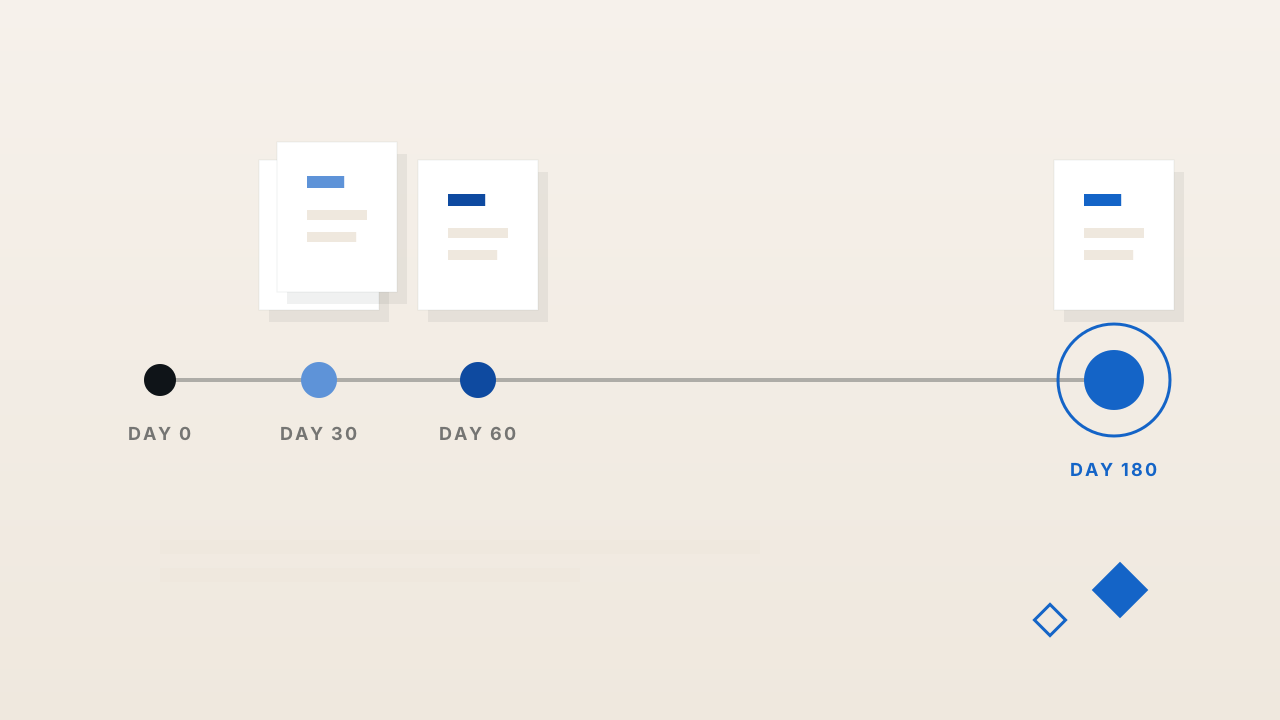
The certificate of incorporation arrives, and it feels like an ending. It is not; it is a starting gun. From the day your company legally exists, a clock starts running on a set of obligations most founders do not know about until they have already missed one. None of these come with a friendly reminder from the MCA. The portal does not nudge you. You are simply expected to know, and the penalties for not knowing are real: ₹1,000 per day for some defaults, director disqualification for others and, at the far end, the Registrar striking your company off the register entirely.
The good news is that the first ninety days are finite and knowable. Here is the whole calendar, in order, so nothing arrives as a surprise.
Within 30 days of incorporation
Hold your first board meeting
A private limited company must hold its first board meeting within 30 days of incorporation. It can be held over video call if your directors are in different cities; what matters is that minutes are recorded and signed. This first meeting is where several of the items below are formally set in motion, so it is the anchor of the whole sequence.
Appoint your first auditor
The board must appoint the company's first statutory auditor within 30 days of incorporation. That auditor holds office until your first Annual General Meeting. This is not optional and not something to defer: every company is audited, whatever its size or turnover, and a company cannot validly close its first year without an auditor appointed at the start of it.
File Form ADT-1
Once the auditor is appointed, Form ADT-1 (notifying the Registrar of the appointment) should be filed within 15 days of the appointment. It is a small filing that keeps your statutory record clean from day one.
Open the company bank account and deposit capital
You will have a current account in the company's name, into which each subscriber deposits the share capital they committed to in the MoA. This step gates the single most important early filing, INC-20A below, because that filing certifies the capital has actually been received.
The 30-day block, in one line. First board meeting, first auditor appointed, ADT-1 filed, bank account opened and capital deposited. Miss the board meeting or the auditor appointment and you have created a defect in your company's very first year of records.
Within 60 days of incorporation
Issue share certificates
Share certificates must be issued to subscribers within 60 days of incorporation. They are the proof of ownership in your company. They are easy to overlook because nobody is chasing you for them, but they matter the moment there is an investor, a dispute or a due-diligence exercise, and reconstructing them later is far harder than issuing them on time. Our investor readiness checklist explains why a clean share record matters so much later.
Within 180 days of incorporation
File Form INC-20A: the one you cannot miss
If there is a single filing to circle in red, it is this one. Form INC-20A, the Declaration of Commencement of Business, must be filed within 180 days of incorporation. It declares that every subscriber has paid for their shares and that your registered office is verified. Until it is filed, your company legally cannot commence business or exercise borrowing powers, and in practice your current account does not function properly.
The penalty structure is deliberately severe: ₹50,000 on the company, and ₹1,000 per day on every officer in default, up to a cap. Worse, the Registrar can begin proceedings to strike your company off the register if it remains unfiled. It is one of the most commonly penalised post-incorporation defaults in India, precisely because nobody prompts it and founders do not know it exists. File it as soon as your capital is in and your office is confirmed; there is no advantage to waiting.
| Deadline | What is due |
|---|---|
| 30 days | First board meeting, with minutes recorded and signed |
| 30 days | First auditor appointed |
| 15 days from appointment | Form ADT-1 filed |
| Early | Bank account opened, capital deposited |
| 60 days | Share certificates issued |
| 180 days | Form INC-20A filed (strike-off risk if missed) |
The registrations that should happen early too
Strictly, these are not all 90-day statutory deadlines, but they belong in the same window because waiting on them creates friction everywhere else:
- GST registration, if your turnover or business type requires it, so you can raise compliant tax invoices. Since November 2025 many small businesses can be registered in three working days.
- Professional tax and Shop Act, which Maharashtra applies from early on: Shop Act within 60 days of starting, and professional tax from your first salaried hire. Our Pune and Maharashtra registrations guide has the detail.
- TAN, before you deduct TDS on rent, contractors or salaries.
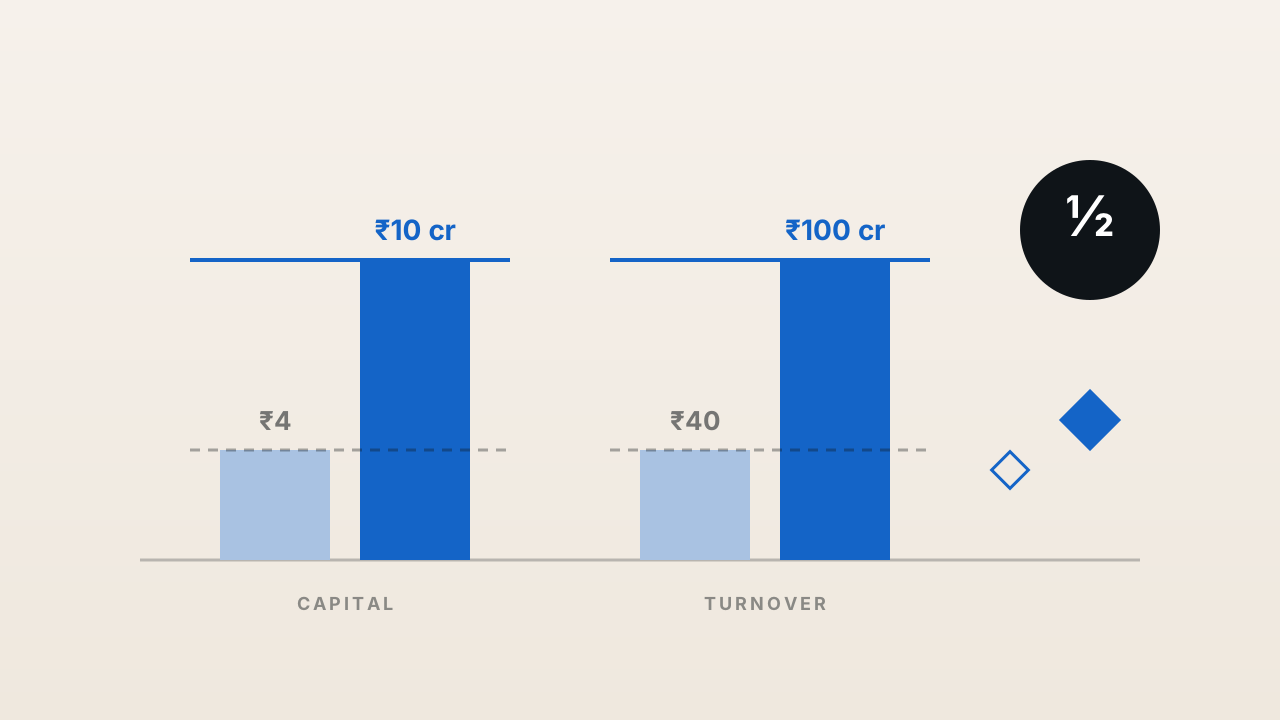
- Udyam (MSME) registration: free, quick, and the gateway to cheaper credit and a halved government fee on trademarks. There is no reason to delay it; see why Udyam is the best first registration.
- Appointment letters for your first hires, which the Labour Codes now make mandatory for every worker.
What the rest of year one looks like
Beyond 90 days, the rhythm becomes annual. AOC-4 (financial statements) and MGT-7 or MGT-7A (annual return) are filed after your AGM; your company's income tax return follows, and, if registered, ongoing GST returns. Director KYC (DIR-3 KYC) changed in 2026: it is now filed once every three financial years, by 30 June, rather than every September. Late ROC filings cost ₹100 per day, per form, and three consecutive years of non-filing can disqualify a director. It compounds quietly, which is exactly why it is dangerous. Our annual ROC filing guide has the full calendar, and most new companies qualify for the lighter small company regime.
One calendar, one contact. Fifteen or more compliance items across the first year is a lot to track on a spreadsheet, and a missed date is a penalty, not a reminder. The point of a proper compliance partner is not the filing itself; it is that you are notified before a deadline, not after. The founder's involvement should be one short monthly review, not a series of panic filings.
Where we fit
We run this calendar so you do not have to memorise it. Company formation includes getting these first filings right, and our virtual accounting service keeps the GST, TDS and ROC obligations ahead of their deadlines on a single monthly rhythm. If you have just incorporated, or you are not sure whether something has been missed, that is a quick conversation, and it is far cheaper than a penalty.
Rasika's Company Registration includes getting these first filings right, and Virtual Accounting keeps GST, TDS and ROC obligations ahead of their deadlines on one monthly rhythm.
This article is general information, current as of 3 October 2026. It is not legal or tax advice for your specific situation.